
Sign up to save your podcasts
Or

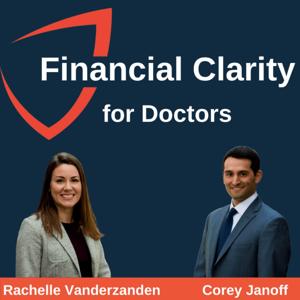


Hosts Corey Janoff and Rachelle Vanderzanden dive into 12 smart moves doctors should make in today's episode of the Financial Clarity for Doctors podcast. We've worked with many doctors and dentists over the years and have observed our fair share of the good, the bad, and the ugly when it comes to money moves. Keep reading and listening if you want to put your best foot forward.
1. Have a Game Plan for Your Student Loans
2. Keep Your Mortgage Under 2x Income
3. Get Own Occ Disability Insurance!
4. Get Life Insurance If You Have (or plan to have) Dependents
5. Get Umbrella Liability Insurance
6. Get an Estate Plan
7. Save 20% of Income for Retirement
8. Max Out Tax-Advantaged Accounts
9. Diversify
10. Don't Chase Returns
11. Earmark Retirement Savings for Retirement
12. Have a Plan to Achieve Your Goals
Most doctors aren't very money savvy. The fact that you are listening to this podcast puts you way ahead of your peer group regarding financial competence. Not all of it is fun. It will take some discipline and dedication to adhere to these principles. However, it is all doable, and you can do it!
This list is by no means complete, but it covers some of the big things to devote attention to on your quest for financial independence.
Baby Step Your Way to Financial Independence
10 Money Moves Savvy Doctors Make
Thanks again to the Financial Clarity Blog, our amazing clients, and the whole team at The Finity Group.
For more financial planning tips from Corey and Rachelle, find them on LinkedIn @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
Hosts Corey and Rachelle dive into the subject of raising children, specifically the cost of raising children.
What makes kids so expensive, you ask?
Impact on Income.
Childcare expenses.
Housing.
Transportation.
Food.
Vacations.
Clothing.
Activities.
Healthcare.
To name a few…
In today’s episode, we’ll cover these expenses with some savvy tips to help you along the way. For many of us who chose to have children, we probably aren’t retiring in our 40’s and jet-setting around the world. And that is perfectly OK.
For more financial planning tips from Corey and Rachelle, find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
Welcome to our 30th episode and one year anniversary of the Financial Clarity for Doctors Podcast!
This week on the podcast, Corey and Rachelle help you better understand how much money doctors need to retire. If you’ve been listening to us for a while now, or have been keeping up on the blog, you might be able to guess today’s question. So, how much money does a doctor need to retire…. It depends!
There are several factors when considering how much you may need, and everyone’s situation is going to be a little different based on your lifestyle, goals, and family situation. In this podcast, we start by digging into what items you need to consider to understand your baseline expenses and the lifestyle you want to live while in retirement.
Once you understand how much money you need and the age you would like to retire by, we need to plan to get to your goal. Again, the right plan for you is going to depend on your current circumstances and needs.
Tip of the day: Get started early and get going often!
For further learning on this subject check out the links below
https://thefinitygroup.com/blog/how-much-money-does-a-doctor-need-to-retire
https://thefinitygroup.com/blog/saving-for-retirement-is-like-biking-across-the-country
https://thefinitygroup.com/blog/retirement-savings-targets-by-age
Thanks again to the Financial Clarity Blog, our amazing clients, and the whole team at The Finity Group.
For more financial planning tips from Corey and Rachelle find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
This week on the podcast, Corey and Rachelle dive deep into Tax Loss Harvesting with our special guest and Chartered Financial Analyst (CFA®), Zach Kill of Finity Group LLC.
In a perfect world, our investments only appreciate in value and we happily pay taxes on our investment earnings. As it turns out, the world isn’t perfect and sometimes investments go down in value. While not ideal, this can present an opportunity to save on taxes by “harvesting” those losses.
In this episode you’ll learn all how to wisely harvest your investment losses to work in your favor to help lower your taxes when applicable. You’ll also learn how to understand capital gains and losses and the tax implications of each.
For higher income earners, taxes are one of your biggest enemies, so any opportunities to reduce your tax burden can be attractive.
Tax-loss harvesting does not come without its catches. To properly tax loss harvest you need to stay diligent about how you’re going about it to avoid things like a wash sale, which would negate your tax benefits.
If done correctly, you will maintain your overall investment strategy while reducing your tax burden over time.
Check out more at Thefinitygroup.com
You've most likely heard of behavioral economics and are familiar with some of the leading theorists, Richard Thaler, Amos Tversky, or Daniel Kahneman, and so on. You may even be able to talk about a few of the main concepts during friendly conversations with friends or family. In today's podcast, our own Finity behavioral economics guru, Owen Chambers, will help take you further into behavioral economics.
We'll dig deep into some of the many behavioral economic concepts to help you better understand your brain and how it may or may not be assisting you when it comes to financial decision making. On your own, are you typically more risk-averse when it comes to making decisions? For example, did you know that you're more likely to be less risk-averse according to the behavioral theory when you're with a group of people than on your own? Or, in a couple or pairing when it comes to money decisions, the more risk-prone individual is often more willing to make a less risky investment out of respect for their less risk-averse partner? These ideas and others like; inflations vs. investment risk, the anchoring effect, hindsight bias, and confirmation bias are discussed in this episode. We guarantee you won't want to miss out!
For more financial planning tips from Corey and Rachelle find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
Ep. 27 How Much House Can a Doctor Afford?
There are a multitude of things to consider when buying a home. In this week's Financial Clarity for Doctors podcast, we help you better understand things to consider when determining how much house you can afford as a doctor. We discuss all the costs associated with purchasing and owning a home, and how to make smart homeownership decisions so you can still achieve your other important financial goals. Below are a few of the topics we cover.
1 - Your neighborhood – will you be feeling the ache to keep up with the Joneses
2 – What about the internal and external work that may need to be done on the house
3 – Are you sure you plan on sticking around for a while? Preparing to sell quickly from the initial time you bought can have adverse financial effects.
4 – Did you calculate all other debt into the equation? If you just completed residency, you are more likely to be paying off a hefty student loan.
Tip of the day: Just because you may be approved for a significant loan from the bank for a bigger or nicer home does not mean you need to take the money. The key to keeping on the path of financial success is to keep your housing cost below 20% of your income.
To learn more about purchasing a home as a doctor, check out the blog posts below:
Cost of Short Term Home Ownership: https://thefinitygroup.com/blog/cost-of-short-term-home-ownership
#1 Predictor of Wealth Accumulation: https://thefinitygroup.com/blog/1-predictor-of-wealth-accumulation
The Doctor Mortgage Loan: https://thefinitygroup.com/blog/the-doctor-mortgage-loan
Thanks again to the Financial Clarity Blog, our amazing clients, and the whole team at The Finity Group.
For more financial planning tips from Corey and Rachelle find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
Physician Contract Review
You worked hard to get where you are today, so it's essential you know what you're stepping into when you select you to make that next big move. Physician contracts can contain convoluted language in your contractual agreement(s); a team can lend you our experience and expertise to ensure that you can make a well-informed decision. If you're making the transition into practice after years of extensive training or looking to further your career with a new employer, having a physician contract review team can help you better understand your contract.
Contractual language can be scary or hard to understand to those unfamiliar, and occasionally essential items to your success and happiness in the role can be overlooked. Most contract reviews will help you by going over the compensation, benefits package, non-compete clauses, duties and obligations, retirement plan information, student loan forgiveness eligibility, and the like.
Understanding the full picture of what you're walking into, especially when you're just starting, can help you get your career on the right track. You spent countless hours and dollars preparing for this career; make sure you're getting what you're worth, and the confidence knowing your offer is comparable to your colleagues.
Learn more about Finity Groups Physician Contract Review services: https://thefinitygroup.com/services/physician-contract-review
Disclosure: We are not attorneys and this material is not to be construed as legal advice. Consult with an attorney licensed in your state for specific legal implications of your employment contract.
Transitioning to Practice
For doctors, one of the most significant life events is transitioning from residency or fellowship into practice. This usually involves a significant pay increase, a job change, possibly a move to a new city, student loan payments increasing, the desire to purchase a house, new car, maybe start a family, among other things. There are many things for physicians to address when it comes to financial planning around this time. If you can set the tone and start your attending career on the right foot, your long-term financial goals will be much more achievable. Today we will discuss setting up a good game plan for your transition to set you up for future financial success.
Creating a plan can be easy when you start with a goal in mind. Assessing your needs now and in the future will help you know what you need to so in the short term to be able to adequately save for retirement, as well as those other bigger purchases you may want down the road. The key is to take it one step at a time.
Tip of the day: Time and money are limited resources. You have to prioritize your goals – answer the question, “what do I want to accomplish?”
For further reading on transitioning to practice check out these blogs: For further reading on transitioning to practice check out these blogs:
Transitioning to Practice: https://thefinitygroup.com/blog/transitioning-from-residency-into-practice
Retirement: https://thefinitygroup.com/blog/how-much-money-does-a-doctor-need-to-retire
https://thefinitygroup.com/blog/saving-for-retirement-is-like-biking-across-the-country
Student Loans: https://thefinitygroup.com/blog/debt-some-guidance-on-how-to-get-rid-of-it
https://thefinitygroup.com/blog/medical-school-loan-dilemma
https://thefinitygroup.com/blog/how-to-qualify-for-public-service-loan-forgiveness
Buying a Home: https://thefinitygroup.com/blog/do-doctors-get-better-mortgage-rates
https://thefinitygroup.com/blog/should-i-buy-a-house-or-keep-renting
https://thefinitygroup.com/blog/the-doctor-mortgage-loan
Thanks again to the Financial Clarity Blog, our amazing clients, and the whole team at The Finity Group.
For more financial planning tips from Corey and Rachelle find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
One thing almost every client asks about as they transition into practice is what to do first. You all have competing goals. If you have debt, you want to pay it off immediately. You also know you’re a little late to the retirement savings game and want a million dollars in savings tomorrow. So how do you figure out what to focus on first?
It depends! What makes sense for you does not necessarily make sense for your co-worker. Avoid the water cooler financial planning. The important thing is to approach strategically and make a plan for your cash flow.
One area to pay attention to is going to be Interest rates. Credit cards and personal loans can be pesky areas where we spend more than we need to be spending. An easy way to tackle interest rates is by lining them up by percentage and working your way down debt, starting highest to lowest.
Thanks again to the Financial Clarity Blog, our amazing clients, and the whole team at The Finity Group.
For more financial planning tips from Corey and Rachelle find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
Own-Occupation Disability Insurance: Do I need it?
Hosts Corey Janoff and Rachelle Vanderzanden dive into detail on the important topic of own-occupation disability insurance. Many doctors have heard from somewhere that they need this, but do they really? When should you get it and why?
What is it? Long-term disability insurance is income protection. If you are unable to work for a few months, a few years, or even suffer from a career ending injury or illness, it will pay out a specific benefit amount. Own-occupation coverage specifies that you are considered disabled if you cannot do your job, even if you can still do something else.
Do I really need disability insurance? Short answer - yes. As a young worker, you build your entire financial plan around an assumption that you will make income in the future. With physicians, that income is generally a very large dollar amount. If we took that out of the plan, what are the chances that it would work?
When should I get coverage? Yesterday. Or the day before you get disabled, but we don’t know when that is. There are two big risks to waiting, 1) you could get disabled without coverage and 2) a medical condition, injury, family diagnosis, or other risk factor could come up that makes it much more difficult, or even impossible, to secure coverage.
How do I get started? There are a handful of companies that offer strong, own-occupation disability insurance coverage. Work with an independent agent to try to find the carrier that works best for you based on cost, underwriting requirements, and what you want in a policy.
Tip of the Day: If you need your income, you need disability insurance.
Thanks again to the Financial Clarity Blog, our amazing clients, and the whole team at The Finity Group.
For more financial planning tips from Corey and Rachelle find them on LinkedIn: @CoreyJanoff and @RachelleVanderzanden; Instagram: @CoreyJanoff and @VanderzandenRachelle; and Twitter: @CoreyJanoffCFP and @RachelleFinance
Discussions in this show should not be construed as specific recommendations, legal, or investment advice. Always consult with your investment professional before making important investment decisions. Advisory services through Cambridge Investment Research Advisors, Inc., a Registered Investment Advisor. Securities offered through Cambridge Investment Research, Inc., a registered Broker/Dealer, Member FINRA/SIPC. Finity Group and Cambridge are not affiliated.
From the publisher's feed
3,565 Listeners

3,233 Listeners

1,966 Listeners

800 Listeners

5,140 Listeners
2,443 Listeners
182 Listeners
227 Listeners

831 Listeners

198 Listeners
39 Listeners
25 Listeners
358 Listeners
26 Listeners
12 Listeners